A bank saying no is frightening when the money is for a bill that cannot wait. What you do next matters more than how fast you find another form.
The short answer after a rejection
One lender said no to one loan product. Work through this before you apply anywhere else.
- Find out what needs attention, then read your Credit Bureau Singapore (CBS) report.
- Work out what you can actually repay each month.
- Choose the route that fits: another bank, a licensed moneylender, a creditor arrangement or support.
No route guarantees approval. The provider assesses the application and decides.
Compare available personal-loan optionsFor the reasons an application gets declined in the first place, read why loans get declined in Singapore.
What does a bank rejection actually mean?
One product, one decision
One bank's decision on one application, under its own product criteria.
Not a payment default, and not a bar on other providers considering you.
Credit Bureau Singapore says previous enquiries are retained for two years, and that lenders read the credit report alongside income and other information.
Frequent or recent applications change how a lender assesses risk. Apply selectively.
What should I do first, and in what order?
Write down the amount, the purpose, the deadline and the repayment you can afford. A new loan can close a short gap and create a longer problem, so note whether the need is temporary.
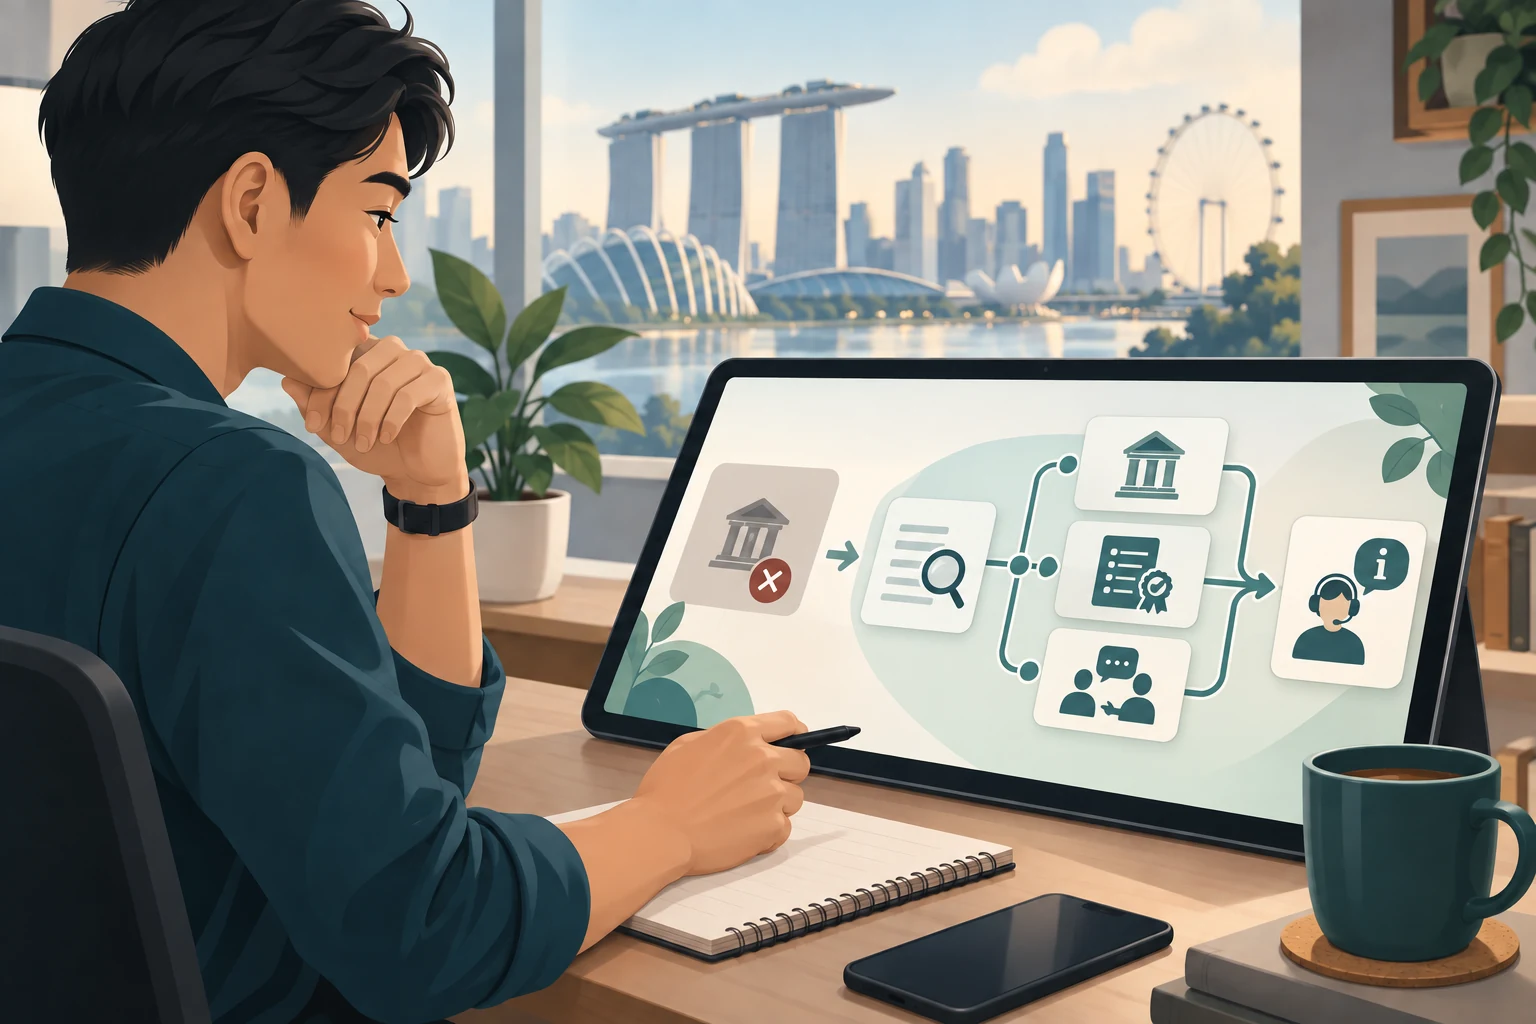
From rejection to your next application
- Understand the decisionAsk what needs attention: documents, income verification, existing commitments, employment information, credit enquiries or product criteria.
- Pause new applicationsRushed applications add enquiry records, and no waiting period guarantees approval.
- Check report and documentsCheck the personal details, repayment history and previous enquiries for errors.
- Know the limitsMAS unsecured-credit rules and the caps below restrict what any provider may offer.
- Decide whether to borrowIf the instalment would make essentials unaffordable, an arrangement or assistance route is safer.
- Compare one routeCheck the actual lender, the cash received, the instalment and the total repayment.
A comparison is not approval, and an indicative offer is not a final contract.
Step three uses your CBS consumer credit report. For high unsecured debt, read the Monetary Authority of Singapore’s Credit Limit Management Measure. At step five, ComCare or Credit Counselling Singapore can beat a loan.
Why might another bank still be unable to lend more?
Three limits that follow you between banks
"Up to 10 times your monthly income" is a product-level example from a bank description or guide, not an entitlement.
Under the Credit Limit Management Measure, once outstanding unsecured debt is above 6 times monthly income, a financial institution cannot grant new unsecured credit that would push the total credit limit above 12 times monthly income.
MAS limits aggregate unsecured debt across all financial institutions, so a second bank may be restricted by your overall position.
Banks may apply stricter internal income, credit-score or product rules. Debt consolidation and refinancing are treated differently, but neither is a general approval route.
How much can a licensed moneylender lend me?
Licensed-moneylender borrowing caps by income
| Annual income | Singapore Citizens and PRs | Foreigners residing in Singapore |
|---|---|---|
| Less than S$10,000 | S$3,000 | S$500 |
| S$10,000 to less than S$20,000 | S$3,000 | S$3,000 |
| S$20,000 or more | 6 times monthly income | 6 times monthly income |
The 6-times figure applies only in the S$20,000-or-more row, and it counts every licensed moneylender together rather than per lender. A lender can approve less.
What can a licensed moneylender charge in Singapore?
For unsecured loans, the official borrower guidance sets these limits.
Legal caps on interest and fees
Capped at 4% per month.
Capped at 4% per month on the amount repaid late.
No more than S$60 for each month of late repayment.
No more than 10% of the principal.
Cannot exceed an amount equivalent to the principal of the loan.
These are legal caps for unsecured loans, not a quote. Ask for the actual rate, fees and schedule in dollars.
Where can I borrow money after a bank rejection in Singapore?
Six routes, and what to check for each
Another bank
- Fits
- The issue may be specific to one product or bank.
- Check
- Eligibility, income, existing commitments and whether a formal credit enquiry is made.
Licensed moneylender
- Fits
- You accept the higher repayment risk of a regulated non-bank option.
- Check
- Licence, contract, interest, fees and repayment schedule.
Existing-creditor discussion
- Fits
- The problem is a bill, arrears or payment timing.
- Check
- Whether an arrangement exists before you borrow to cover old debt.
Government or community assistance
- Fits
- The need is essential living support that borrowing may worsen.
- Check
- Official eligibility and application channels.
Debt advice
- Fits
- Existing repayments are already hard to manage.
- Check
- Whether Credit Counselling Singapore can help first.
Do nothing yet
- Fits
- The need is not urgent, or the repayment is unaffordable.
- Check
- Whether waiting or fixing your records beats applying now.
The route depends on urgency, the rejection reason and affordability. None guarantees approval.
The Ministry of Law’s borrower guidance tells borrowers to consider alternatives, borrow only what they can repay, understand the contract and shop around. Verify any moneylender offer against the current list of licensed moneylenders. A licence does not make a loan suitable.
When should you not borrow?
When to walk away, and when to pause
- Approval is guaranteed without checking your information.
- An unexplained upfront payment must be paid first.
- Someone asks for your Singpass password, one-time code or bank login.
- The actual lender will not be named.
- The repayment schedule and total cost are hidden.
- You are pushed to accept or sign before you understand the contract.
- Threats or unclear explanations are used.
- Rent, food, transport or utilities would become unaffordable.
- You are borrowing to pay another loan with no repayment plan.
- You do not know the total you will repay.
- You feel panicked or embarrassed into applying.
- The provider cannot be independently verified.
Never share a password or one-time code with a lender, an intermediary or anyone contacting you online. There is no shame in deciding that not borrowing today is safer.
The Registry of Moneylenders says unsolicited loan SMSes and calls may be linked to unlicensed moneylending. Do not reply. Follow the Singapore Police Force guidance on unlicensed moneylending, or report it through the borrower guidance channels.
What should I confirm before applying again?
Six things you should be able to say yes to
- I know the amount, the purpose and the deadline.
- I know what needs attention after the bank's decision.
- I can afford the instalment after existing bills.
- I know the legal name, and whether it is a bank, a licensed moneylender or a platform.
- I know the cash received, the instalment, the number of instalments, the total repayable and every charge.
- I verified any moneylender on the official list, and nobody asked for a password, code or unexplained fee.
If any are unanswered, pause. An indicative offer is not approval, and you can stop at any point.
Where does a comparison platform fit?
A comparison platform shows what may be available without contacting every provider. It is not the lender and it cannot approve a loan.
PickMeALoan describes its public flow as one form, then personalised options from banks and licensed lenders. You compare and choose whether to continue; the provider assesses and decides. You can start with PickMeALoan, then check the lender, total repayment and affordability.
Frequently asked questions
Visible answers
What should I do if my bank loan is rejected?
Pause, ask what needs attention, check your information and existing commitments, and compare regulated options only after confirming that repayment is affordable.
Where can I borrow money after a bank rejection in Singapore?
Possible routes include another bank, a licensed moneylender or a non-borrowing support route. The right route depends on your circumstances; no route guarantees approval.
Can I apply to another lender immediately?
You may be able to, but avoid several rushed formal applications. Understand the first decision, check your CBS report and compare the next option before proceeding.
How do I check that a moneylender is licensed?
Use the Ministry of Law's current list of licensed moneylenders and verify the exact lender named in the offer. Do not rely on an advertisement or message alone.
Does PickMeALoan guarantee approval?
No. PickMeALoan is a comparison platform. The provider assesses the application and decides whether to make an offer or approve a loan.
How much can I borrow from banks and licensed moneylenders in Singapore?
There is no universal bank rule that every borrower can receive 10 times monthly income. MAS aggregate unsecured-credit rules can restrict new credit across financial institutions, while licensed moneylenders have statutory caps across all moneylenders: 6 times monthly income applies from annual income of S$20,000, with lower fixed caps below that threshold. Each provider can be stricter.
Sources and last checked date
Public sources checked 21 September 2026:
- Ministry of Law Registry of Moneylenders: borrower guidance
- Ministry of Law: list of licensed moneylenders
- Credit Bureau Singapore: consumer credit report
- Credit Bureau Singapore: credit report explanation
- Monetary Authority of Singapore: Credit Limit Management Measure
- Monetary Authority of Singapore: borrowing limit on unsecured credit
- MSF: ComCare
- Singapore Police Force: unlicensed moneylending
- PickMeALoan
- PickMeALoan privacy policy
PickMeALoan is a loan comparison platform, not a lender. Loan offers, terms and approval depend on the provider’s assessment and verification.